By Edvin Jones, Attorney at Law | Edvin Jones Injury Law | insurance adjuster tactics
Quick Takeaways:
- You do not have to accept an insurance settlement simply because an adjuster offers one.
- Early offers may not account for future medical treatment, lost income, or the full impact of an injury.
- A signed settlement release will generally prevent you from pursuing additional compensation for the claims it covers.
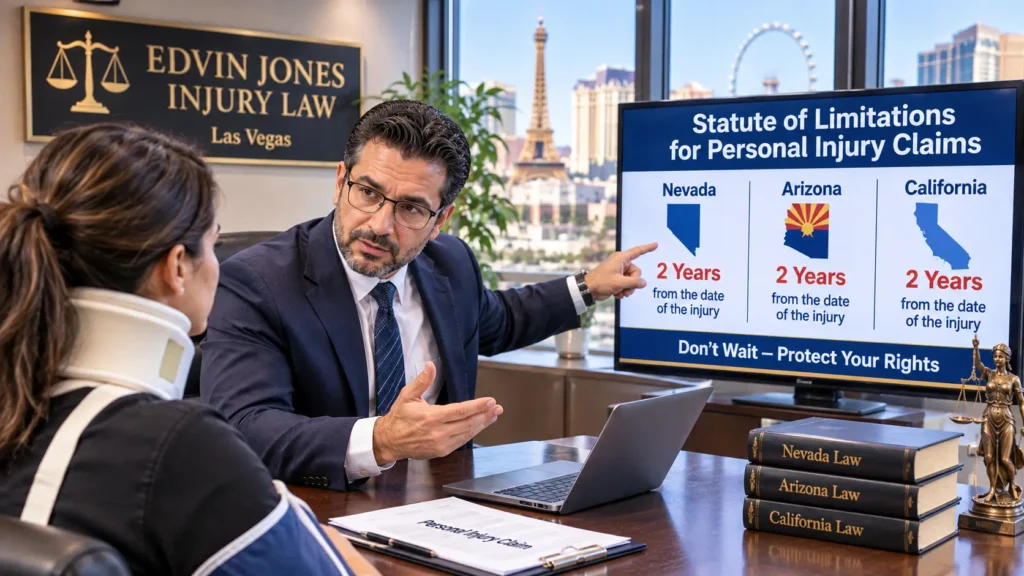
- Nevada, Arizona, and California apply different comparative negligence rules that can affect your potential recovery.
- Before accepting an offer, understand your injuries, losses, policy requirements, and the terms of the proposed release.
- A personal injury attorney can review an offer, explain insurance adjuster tactics, and explain your options before you make a final decision.
After an accident, an insurance adjuster may contact you quickly. The adjuster may sound friendly and sympathetic—and may be ready to make a settlement offer.
But should you accept it?
Not without understanding what you are giving up. An early offer may be lower than the full value of your claim, particularly when you have not completed medical treatment or learned whether your injuries will have lasting effects.
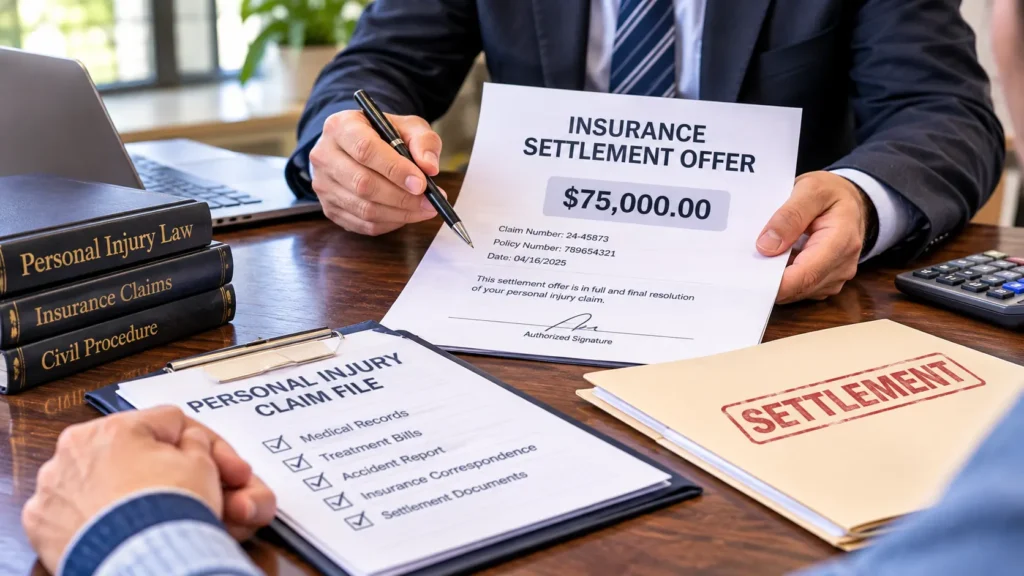
In many cases, signing a settlement agreement and release is final. You may give up the right to seek additional compensation for the injuries and losses covered by that agreement, even if your condition later worsens.
Before accepting an offer in Nevada, Arizona, or California, take time to understand your claim and the consequences of settling.
Why the First Settlement Offer May Be Too Low
An initial offer is not necessarily a complete assessment of your losses. It may be made before important information is available, including:
- The full extent of your injuries: Some injuries take time to diagnose, and symptoms may develop or become more serious after the accident.
- Future medical expenses: You may need additional treatment, physical therapy, medication, or surgery.
- Lost income and earning capacity: An injury can affect your ability to work, reduce your hours, or limit your future employment options.
- Pain and suffering: The physical discomfort and emotional impact of an injury may be difficult to evaluate early in the process.
- Other accident-related losses: Transportation to medical appointments, out-of-pocket expenses, and other documented costs may also matter.
Insurance companies evaluate claims based on the available evidence, policy terms, liability issues, and other factors. An early offer may reflect an incomplete picture of your injuries and damages.
That is why it is important to understand what the offer covers before deciding whether to accept it.
Common Issues to Watch for When Dealing With an Insurance Adjuster
Insurance adjusters handle claims on behalf of insurance companies. Their questions and settlement proposals are part of the claims process, but you should understand how your statements and decisions may affect your case.
Here are several situations that deserve attention:
1. Requests for Recorded Statements
An adjuster may ask you to provide a recorded statement about the accident and your injuries.
Your words may later be reviewed when the insurer evaluates liability or the extent of your injuries. An incomplete or inaccurate description could create confusion about what happened or how you were affected.
Whether you must provide a statement depends on your role in the claim, the applicable policy, and other circumstances. Before agreeing, understand who is requesting it and whether you have a contractual or legal obligation to cooperate.
2. Pressure to Settle Quickly
An adjuster may offer payment soon after an accident. A quick settlement can seem attractive, especially when medical bills and lost income are creating financial stress.
However, settling before you understand your diagnosis, treatment needs, and recovery outlook can create problems. Once you sign a release, you may be unable to seek additional compensation for covered injuries later.
3. Social Media Posts
Photos, videos, and comments on social media may become relevant to an insurance claim.
For example, a post showing you participating in an activity could be interpreted as inconsistent with limitations you reported. But a single photograph rarely tells the whole story of someone’s medical condition.
Avoid discussing the accident or your claim publicly, and do not misrepresent your condition. Preserve relevant evidence and speak with an attorney if you are unsure how social media activity may affect your case.
4. Suggestions That You Do Not Need an Attorney
You may hear that hiring a lawyer is unnecessary or that the insurance company can handle everything directly.
Some straightforward claims may be resolved without an attorney. However, if you have significant injuries, disputed fault, ongoing treatment, or a settlement offer you do not understand, independent legal advice may help you evaluate your options.
You should be able to make an informed decision without feeling pressured.
Why Nevada, Arizona, and California Rules Matter
The state where your accident occurred can affect how your compensation is calculated if you share responsibility for the accident.
Nevada, Arizona, and California do not use identical comparative negligence rules.
Nevada: Modified Comparative Negligence
Nevada follows a modified comparative negligence system under NRS 41.141.
Generally, you may recover damages if your negligence is not greater than the negligence of the defendant or defendants whose fault is being compared. Your compensation is reduced by your percentage of responsibility.
If your negligence is greater than the combined negligence of the defendant or defendants, you generally cannot recover.
For example, if you have $100,000 in damages and are found 40% responsible, your potential recovery would be reduced to $60,000, subject to the evidence and applicable law.
Arizona: Pure Comparative Negligence
Arizona follows a pure comparative negligence system under A.R.S. § 12-2505.
You may generally recover damages even if you were primarily responsible for the accident. Your compensation is reduced according to your percentage of fault.
For example, if you have $100,000 in damages and are found 70% responsible, your potential recovery would generally be $30,000.
California: Pure Comparative Negligence
California also follows a pure comparative negligence system.
As in Arizona, your recovery is generally reduced by your percentage of responsibility. Even if you were more than 50% at fault, you may still be able to recover a reduced amount.
For example, if your damages are $100,000 and you are found 70% responsible, your potential recovery would generally be $30,000.
These examples are simplified. The actual value of a claim depends on the evidence, applicable law, insurance coverage, and other case-specific factors.
Understanding the rules in the state where your accident occurred can help you assess whether an insurance company’s fault argument or settlement offer is reasonable.
What to Consider Before Signing a Settlement Agreement
Before accepting an insurance offer, take the following steps:
- Understand your medical condition. Find out whether your treatment is complete or whether additional care may be necessary.
- Calculate your losses. Consider medical bills, future treatment, lost wages, reduced earning capacity, and other accident-related expenses.
- Review the settlement terms. Understand which claims, injuries, and parties are covered by the release.
- Understand your obligations. Check any applicable insurance policy requirements and deadlines before making decisions about statements or documents.
- Consider getting legal advice. An attorney can review the offer, explain relevant state laws, and help you understand the potential consequences of accepting or rejecting it.
You should not assume that an insurer’s first offer is unfair—or that it is sufficient. The important question is whether it reasonably accounts for your injuries, losses, and the risks of your particular case.
A Settlement Release Can Be Final
One of the most important things to understand is the effect of signing a settlement release.
A release will generally prevent you from pursuing additional compensation for the claims it covers. This may remain true even if you later discover that your injuries require more treatment than you initially expected.
The exact effect depends on the agreement’s language and applicable law. Read the entire document carefully before signing, and make sure you understand what rights you are giving up.
Do not let financial pressure or a short deadline prevent you from reviewing the offer properly.
How Edvin Jones Injury Law Can Help
At Edvin Jones Injury Law, we help accident victims evaluate insurance settlement offers and understand their options in Nevada, Arizona, and California.
We can review the available evidence, consider the impact of comparative negligence rules, assess documented losses, and explain the potential consequences of signing a settlement release.
You do not have to make this decision without understanding your options. We offer a free consultation and handle qualifying injury cases on a contingency-fee basis under a written agreement.
Before accepting an offer, make sure you understand what your claim may be worth and what you may be giving up.
Contact Us
Edvin Jones Injury Law | Edvin Jones, Attorney at Law
Contact Edvin Jones Injury Law — Free Consultation
No Win, No Fee. We Speak English, Farsi, Turkish, Russian & Arabic.
Address:
Phone: 702-337-3430
Website: edvin.law
Instagram: edvinjonesinjurylaw | TikTok: edvin.law
Licensed in Nevada | Arizona | California
Disclaimer: This article is for informational purposes only and does not constitute legal advice. Reading this article does not create an attorney-client relationship.
Frequently Asked Questions (FAQ)
1. Should I accept the first settlement offer from an insurance company?
Not without reviewing it carefully. An early offer may not account for the full extent of your injuries, future medical needs, lost income, or other damages. Consider getting legal advice before accepting.
2. Can I negotiate an insurance company’s first offer?
In many cases, yes. You may be able to provide additional documentation, explain why the offer does not reflect your losses, and make a counteroffer. The available options depend on the claim and applicable policy terms.
3. What happens if I sign an insurance settlement release?
A signed release generally prevents you from pursuing additional compensation for the claims it covers. Review the language carefully before signing because you may be giving up important legal rights.
4. Can I still recover compensation if I was partly at fault?
Potentially, yes. Nevada uses modified comparative negligence, while Arizona and California generally use pure comparative negligence. Your percentage of fault can affect the amount you recover.
5. Do I have to give the insurance adjuster a recorded statement?
It depends on your role in the claim and any applicable policy obligations. Before providing a recorded statement, understand who is requesting it, why it is needed, and whether you are required to cooperate.
6. Should I hire a personal injury lawyer before accepting an offer?
Legal representation is not required for every claim. However, an attorney may help if your injuries are serious, your treatment is ongoing, fault is disputed, or you are unsure whether the settlement adequately accounts for your losses.
7. Does Edvin Jones Injury Law offer free consultations?
Yes. Edvin Jones Injury Law offers free consultations for accident victims seeking to understand their legal options in Nevada, Arizona, and California. Call 702-337-3430 to discuss your situation.